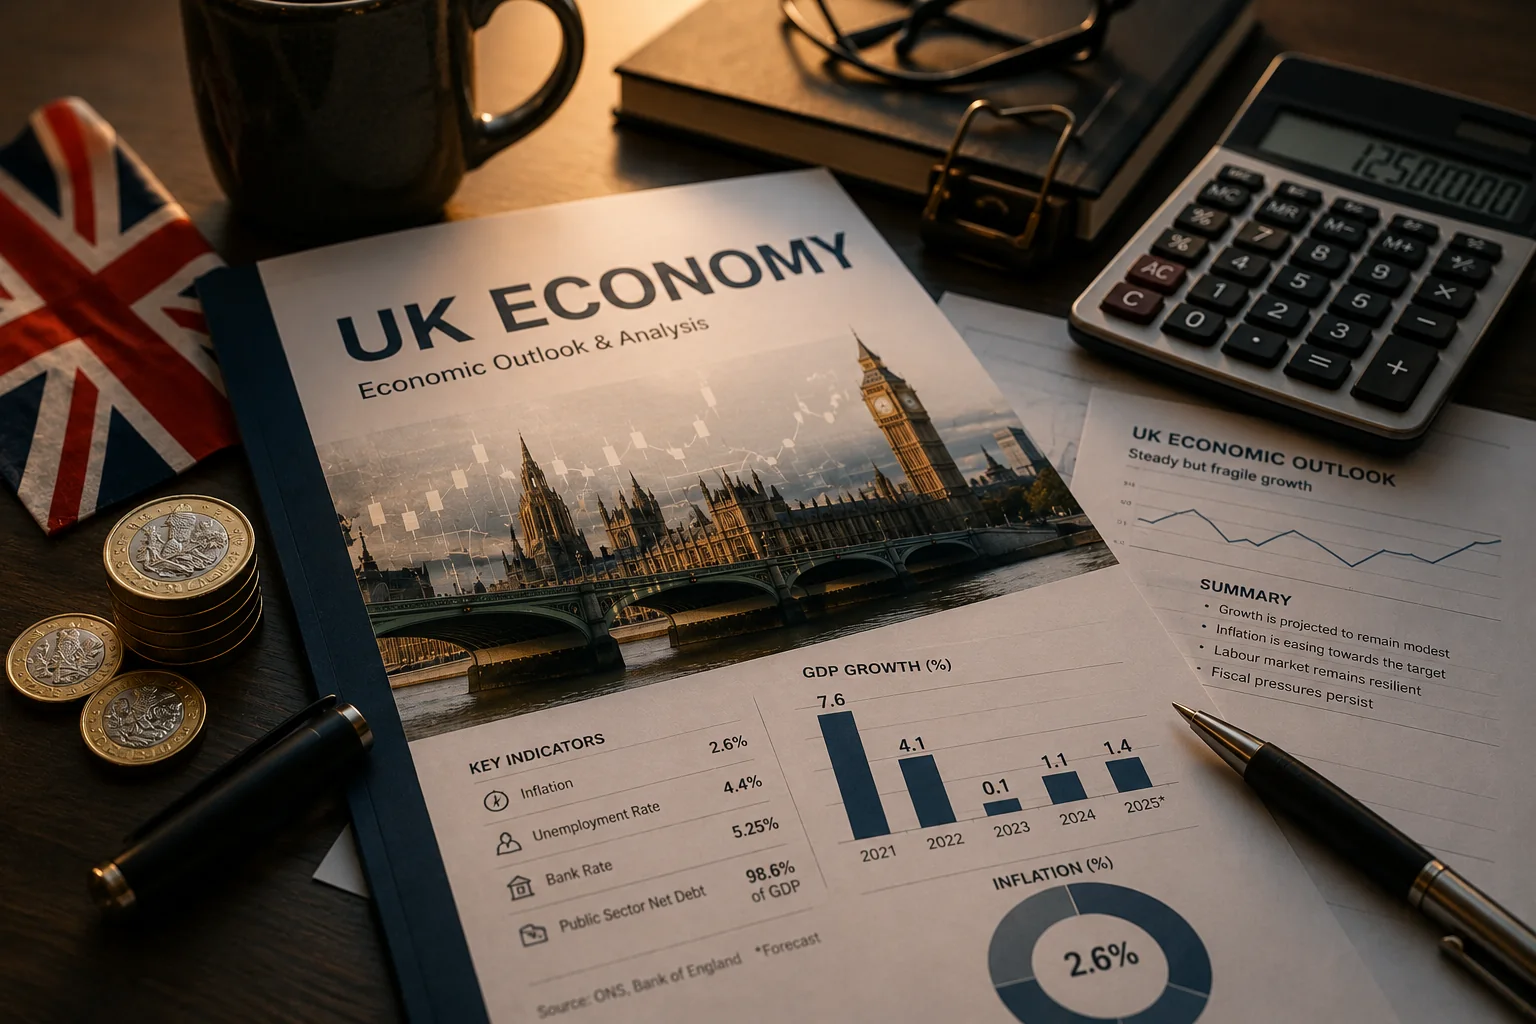
A planned rise in UK interest rates could increase the cost of borrowing for millions of people, affecting mortgage payments as well as credit cards and personal loans.
The impact is expected to vary between households, depending on the type of borrowing they have and how their repayments are linked to interest rates. People with mortgages could face higher monthly bills, while borrowers using credit cards or loans may also see their costs increase.
One example highlights a mortgage payment rising by £200, illustrating the potential pressure higher rates could place on household finances. The material supplied does not identify the borrower or provide further details about the mortgage arrangement.
The rise in rates has not yet been accompanied by details of the scale or timing of the increases faced by individual borrowers. The latest position is that mortgages, credit cards and loans could become more expensive as UK interest rates rise.